
How to Make a Financial Plan Using 5 Essential Calculators
How to create a financial plan becomes much easier when you can see exactly how much money comes in, where it goes, and how today’s financial decisions may affect your future.
You do not need complicated spreadsheets or advanced financial knowledge to get started. A useful personal financial plan begins with a few practical questions: How much can I comfortably spend on housing? What will a car actually cost each month? How much should I save? And how much money should I set aside for everyday purchases?
Five essential financial calculators can help answer those questions.
The Mortgage Calculator estimates housing costs. The Auto Loan Calculator helps you evaluate transportation financing. The Compound Interest Calculator projects potential savings growth. The Sales Tax Calculator shows the actual cost of taxable purchases, while the Tip Calculator helps you plan restaurant spending and shared bills.
By combining these tools with your income, debt obligations, savings goals, and regular expenses, you can build a financial plan that reflects your real circumstances instead of relying on guesswork.
In this guide, you will learn how to create a financial plan using five practical calculators from My Panda Tools, with formulas, realistic examples, and a complete monthly budgeting example.
What Is a Personal Financial Plan?
A personal financial plan is a practical roadmap for managing your money based on your current financial situation and future goals.
It connects your income, expenses, savings, debts, and financial priorities so you can make more informed decisions about how to use your money.
For example, your financial plan might help you determine whether you can afford a new home, replace your car, increase your savings, pay down debt, or prepare for a major upcoming expense.
A useful personal financial plan generally addresses several areas:
- Monthly income and essential living expenses
- Housing and transportation costs
- Outstanding debts and repayment obligations
- Emergency savings and future financial goals
- Retirement and long term planning
- Everyday spending and discretionary purchases
The Consumer Financial Protection Bureau recommends understanding your income, tracking expenses, and establishing a realistic budget as part of managing your money and working toward savings goals.
Why Financial Planning Matters
Imagine two people who earn the same salary.
The first knows how much money is available after regular expenses, saves consistently, and plans ahead for major purchases.
The second makes spending decisions based mainly on the current bank balance, without accounting for upcoming bills or future financial obligations.
Their incomes may be identical, but their financial plans are very different.
Personal financial planning helps you understand the trade offs between spending money today and preserving it for future needs.
For instance, choosing a more expensive car could reduce the amount available for retirement contributions or emergency savings.
A higher mortgage payment might mean you need to reduce discretionary spending or delay another financial goal.
Understanding those trade offs before making a commitment can help you avoid a budget that looks manageable on paper but becomes difficult to maintain.
How Financial Calculators Support Your Plan
Financial calculators convert your assumptions into numerical estimates.
Instead of wondering whether a particular mortgage might fit your budget, you can enter a home price, down payment, interest rate, and loan term to estimate the monthly cost.
You can use a similar approach to compare car loans, estimate long term savings growth, and calculate everyday spending.
However, a calculator does not replace a complete financial plan.
It provides a numerical estimate based on the information you enter. You still need to account for personal circumstances, unexpected expenses, changing costs, and financial priorities.
How to Create a Financial Plan Step by Step
If you are wondering how to plan your finances, start with your current financial position rather than immediately choosing a savings target or buying a financial product.
A financial plan should explain what you can realistically afford today while helping you prepare for the future.
Step 1: Calculate Your Monthly Take Home Income
Start with the money your household actually receives after applicable taxes and payroll deductions.
Suppose your annual gross salary is $90,000.
Your gross monthly income is:
$90,000 ÷ 12 = $7,500
However, $7,500 is not necessarily the amount deposited into your bank account.
Federal and state income taxes, Social Security, Medicare, health insurance, retirement contributions, and other deductions can reduce your take home pay.
For your monthly spending plan, use your actual net income from your pay statements rather than assuming gross income is available to spend.
If your income changes from month to month, review several months of earnings and use a realistic planning estimate.
Step 2: Identify Fixed and Variable Expenses
Fixed expenses are payments that typically remain relatively consistent from month to month.
Examples include rent or mortgage payments, car loans, insurance premiums, and some subscription services.
Variable expenses change according to your spending habits or circumstances.
These may include groceries, fuel, utilities, restaurant visits, clothing, entertainment, and household purchases.
Look through recent bank statements, credit card statements, bills, and receipts to estimate what you normally spend.
The CFPB recommends reviewing several months of spending so that irregular expenses, such as insurance bills, repairs, gifts, and seasonal costs, are not overlooked.
Step 3: List Your Financial Goals
Your goals should be specific enough to calculate.
Instead of writing “save more money,” you might set a goal to accumulate $6,000 in an emergency fund over the next 12 months.
That gives you a measurable target:
$6,000 ÷ 12 = $500 per month
Other goals may include reducing credit card debt, saving for a vehicle down payment, building retirement savings, or preparing for a future home purchase.
Assign each goal a target amount and approximate time horizon.
Step 4: Evaluate Major Financial Commitments
Housing and transportation are common sources of significant recurring expenses.
Before purchasing a home or financing a vehicle, estimate the complete monthly cost rather than focusing only on the advertised price or loan payment.
A home may require property taxes, insurance, maintenance, and HOA fees.
A vehicle may require insurance, fuel, maintenance, registration, and repairs in addition to the loan payment.
Use financial planning tools to estimate these commitments before adding them to your budget.
Step 5: Build Savings Into Your Budget
Savings should be a planned category rather than simply whatever remains at the end of the month.
You may want separate savings allocations for emergencies, upcoming purchases, and long term goals.
For money needed soon, consider the importance of liquidity and protecting your principal. Long term investment planning involves different risks and considerations.
A compound interest calculator can help you explore potential growth, but projected returns should never be treated as guaranteed income.
Step 6: Review Your Plan Regularly
Your financial plan should change when your circumstances change.
A new job, higher rent, increased insurance premiums, a new child, or a major purchase can all affect your spending capacity.
Review your budget monthly and revisit larger financial goals whenever your income, expenses, or priorities change.
The following five calculators help turn this planning process into practical numbers.
1. Estimate Your Monthly Housing Costs
Housing is one of the most important parts of a personal financial plan because it can represent a substantial portion of monthly spending.
If you are planning to purchase a home, start by estimating your complete housing payment.
You can use the My Panda Tools Mortgage Calculator to compare home prices, down payments, mortgage rates, and repayment terms.
The calculator also supports estimated property taxes, homeowners insurance, HOA fees, and private mortgage insurance.
How to Calculate Monthly Mortgage Payment
For a standard fixed rate mortgage, the principal and interest payment is estimated using the loan amount, interest rate, and repayment term.
The formula is:
Where:
- M = monthly principal-and-interest payment
- P = mortgage principal
- r = monthly interest rate
- n = total number of monthly payments
Suppose you are considering a home priced at $350,000.
You plan to make a $70,000 down payment, giving you a mortgage of $280,000.
At an illustrative 6% fixed interest rate over 30 years, the principal-and-interest payment would be approximately $1,679 per month.
However, that is not necessarily your complete housing cost.
Use a Mortgage Calculator With Taxes and Insurance
When learning how to calculate monthly mortgage payment, remember that the amount paid toward principal and interest may be only one component of the total payment.
Consider the same $350,000 home.
| Housing expense | Estimated monthly amount |
| Principal and interest | $1,679 |
| Property taxes | $300 |
| Homeowners insurance | $150 |
| HOA fees | $0 |
| Mortgage insurance | $0 |
| Total estimated housing payment | $2,129 |
All figures are illustrative, not current lender quotes or location-specific tax and insurance estimates.
The difference between the principal-and-interest payment and the total housing payment is $450 per month.
The CFPB explains that taxes, homeowners insurance, applicable mortgage insurance, and HOA fees should be included when evaluating total monthly homeownership costs.
A mortgage calculator with taxes and insurance therefore provides a more useful estimate than a principal-and-interest calculation alone.
You should also maintain a separate allowance for repairs, utilities, and other ownership expenses that may not appear in your mortgage payment.
How Much House Can I Afford Based on Income?
The question how much house can I afford based on income cannot be answered using salary alone.
Two people with identical incomes may have different housing budgets because one has substantial debts or childcare expenses while the other has relatively few financial obligations.
Start by identifying a total monthly housing payment that fits within your household budget.
Then use the Mortgage Calculator to test different home prices and financing arrangements.
If an estimated $2,129 monthly housing payment leaves insufficient money for food, transportation, savings, and other necessities, a lower-priced property or a different financing scenario may be more appropriate for your budget.
Mortgage preapproval is also different from personal affordability. The amount a lender is willing to finance may not be the amount you are comfortable spending.
How Does Down Payment Affect Mortgage Payment?
A down payment reduces the amount you need to borrow.
For example, on a $350,000 home:
| Down payment | Estimated loan amount |
| 5% — $17,500 | $332,500 |
| 10% — $35,000 | $315,000 |
| 20% — $70,000 | $280,000 |
With the same rate and loan term, borrowing less generally reduces the monthly principal-and-interest payment.
A smaller down payment may also result in additional mortgage insurance costs, depending on the loan program.
However, putting all your available savings toward a down payment can leave you without sufficient cash for closing costs, moving expenses, emergencies, and repairs.
Monthly Mortgage Payment With Property Taxes
Property taxes may be paid through your mortgage escrow account or separately, depending on the loan arrangement.
For budgeting purposes, divide the estimated annual property tax bill by 12.
For example:
$3,600 annual property tax ÷ 12 = $300 per month
If your annual homeowners insurance premium is $1,800:
$1,800 ÷ 12 = $150 per month
Add those amounts to your principal and interest estimate.
Property taxes and insurance can change, so review them periodically rather than assuming your initial housing estimate will remain unchanged forever.
Financial planning action: Use the Mortgage Calculator to determine a realistic total housing budget before deciding which home price to target.
2. Calculate Your Car Loan and Transportation Budget
A vehicle purchase affects more than your monthly loan payment.
You also need to budget for insurance, fuel, maintenance, registration, parking, and unexpected repairs.
Start by using the My Panda Tools Auto Loan Calculator to estimate financing costs.
The tool allows you to enter vehicle price, down payment, trade-in value, outstanding trade-in debt, sales tax, fees, APR, and loan term.
How to Calculate Car Loan Payment
A standard fixed-rate auto-loan payment depends on the amount financed, interest rate, and repayment term.
Suppose you are considering a vehicle priced at $28,000.
You plan to make a $5,000 down payment.
Before additional taxes or fees, the amount financed would be:
$28,000 − $5,000 = $23,000
Now add any taxes, registration costs, dealer charges, or other expenses you plan to finance.
If you have a trade-in, account for its value and any outstanding loan balance.
Enter the resulting amount, expected APR, and repayment term into the Auto Loan Calculator.
Compare multiple loan terms rather than evaluating just one monthly payment.
How Much Car Payment Can I Afford?
If you are asking how much car payment can I afford, begin with the amount available in your existing budget.
Suppose you can allocate $650 per month toward all transportation expenses.
Your estimated monthly costs might look like this:
| Transportation expense | Monthly amount |
| Car loan payment | $400 |
| Auto insurance | $120 |
| Fuel | $80 |
| Maintenance savings | $50 |
| Total transportation budget | $650 |
These are illustrative amounts; actual costs vary by vehicle, location, driving habits, and insurance coverage.
A $650 car loan by itself would consume the entire transportation budget before insurance or maintenance.
The CFPB recommends considering the complete cost of purchasing and operating a car, including financing, insurance, fuel, and routine maintenance, when deciding how much to borrow.
Car Loan Monthly Payment With Down Payment
A larger down payment generally lowers the amount you need to finance.
Consider a $30,000 car before taxes and fees:
| Down payment | Amount financed |
| $2,000 | $28,000 |
| $5,000 | $25,000 |
| $8,000 | $22,000 |
If the interest rate and repayment term remain unchanged, reducing the amount financed generally reduces the monthly payment and total interest expense.
However, your down payment should not leave you without sufficient cash for insurance, essential living expenses, or emergencies.
How Does Interest Rate Affect Car Payment?
A higher interest rate increases the borrowing cost of a vehicle.
For example, financing $25,000 at 6% will generally cost less than financing the same amount at 12% over an identical repayment term.
The actual rate you receive depends on your lender, credit profile, loan amount, vehicle, and other underwriting factors.
Use the calculator to compare multiple APR scenarios and review the total interest, not only the monthly payment.
Understand the Total Cost of a Car Loan
A longer repayment term can reduce the required monthly payment while increasing the total amount of interest paid.
For this reason, the total cost of a car loan is an essential part of financial planning.
The CFPB recommends evaluating the amount financed, APR, loan term, fees, and overall borrowing cost when comparing auto loans.
Also consider whether rolling negative equity from an existing vehicle into a new loan would increase the amount you owe.
Financial planning action: Calculate the complete transportation budget first, then determine the car payment that fits within it.
3. Plan Your Savings With Compound Interest
Saving money is an important part of financial planning, but the amount you save each month is only one factor in determining how much you may accumulate over time.
Your initial savings balance, regular contributions, interest rate, compounding frequency, and savings period can all affect the projected result.
A Compound Interest Calculator helps you explore these variables and understand how consistent contributions may affect your future savings.
How to Calculate Compound Interest
Compound interest is interest earned on both the original principal and previously accumulated interest.
Unlike simple interest, which is calculated on the original principal, compound interest allows interest to earn additional interest over time.
The basic formula is:
Where:
- A = future value
- P = initial principal
- r = annual interest rate expressed as a decimal
- n = number of compounding periods per year
- t = number of years
For example, suppose you deposit $5,000 into an account earning a hypothetical fixed annual rate of 5%, compounded annually.
After one year:
$5,000 × 1.05 = $5,250
During the second year, interest is calculated on $5,250 rather than only the original $5,000.
This illustrates how compounding works.
However, actual savings account rates can change, and investment returns are not guaranteed.
Compound Interest With Monthly Contributions
For personal financial planning, regular contributions are often more relevant than a single initial deposit.
Suppose you begin with no savings but contribute $200 at the end of every month for 10 years.
Your total contributions would equal:
$200 × 120 months = $24,000
If you assume a constant 5% annual rate compounded monthly, the projected future value would be approximately $31,056.
Of that amount:
| Savings component | Approximate amount |
| Your contributions | $24,000 |
| Hypothetical compound growth | $7,056 |
| Projected future value | $31,056 |
This is a mathematical illustration, not a forecast or guaranteed investment return. It excludes taxes, fees, inflation, and changes in the assumed rate.
The Investor.gov Compound Interest Calculator allows users to enter initial savings, monthly contributions, investment duration, estimated interest rate, and compounding frequency.
You can use a similar process with the My Panda Tools calculator to test different savings scenarios.
How Much Will My Savings Grow in 10 Years?
If you’re asking how much will my savings grow in 10 years, calculate several scenarios instead of relying on one expected return.
For example, enter an initial balance of $1,000 and monthly contributions of $200.
Then compare the projected results using hypothetical annual rates of 3%, 5%, and 7%.
The purpose is to see how different assumptions affect the calculation, not to predict which return you will actually receive.
You can also compare what happens if you contribute $250 instead of $200 each month.
Increasing your contribution by $50 means depositing an additional:
$50 × 120 months = $6,000
over 10 years, before accounting for any interest or investment growth.
Compound Interest Monthly vs. Annually
The difference between compound interest monthly vs annually is how often earned interest is added to the principal.
With annual compounding, interest is added once a year.
With monthly compounding, interest is added 12 times a year.
For the same nominal annual rate and all else equal, monthly compounding generally produces slightly more growth than annual compounding.
For example, $1,000 earning a hypothetical fixed 5% annual rate for one year would grow to:
$1,050 with annual compounding
or approximately:
$1,051.16 with monthly compounding
The difference may be small over a short period but can become more noticeable over longer periods.
Actual savings and investment products may use different interest crediting methods, fees, and rate structures.
Future Value of Savings With Monthly Deposits
When calculating the future value of savings with monthly deposits, the timing of contributions also matters.
Money deposited earlier has more time to potentially earn interest.
That is one reason consistent saving can be useful when building long-term financial goals.
However, not every savings goal should rely on an investment growth assumption.
Money needed for an upcoming bill or a near-term emergency may require a different approach from money set aside for retirement decades in the future.
Consider your time horizon, access to funds, and risk tolerance before deciding where to keep your savings.
Financial planning action: Set a realistic monthly savings target, enter it into the Compound Interest Calculator, and compare short-term and long-term scenarios.
4. Include Sales Tax in Everyday Purchases
A financial plan should reflect the amount you actually spend, not simply the prices displayed on store shelves or online product listings.
In the United States, many purchases may be subject to state and local sales taxes.
These taxes can increase the final checkout price and affect your shopping budget.
The My Panda Tools Sales Tax Calculator allows you to estimate sales tax, calculate the final purchase price, and work backward from a tax-inclusive total.
Its state presets represent state-level rates, so local taxes may need to be entered separately when applicable.
How to Calculate Sales Tax
The basic formula is:
Sales Tax = Pre-Tax Purchase Price × Tax Rate
Suppose an item costs $100 and the applicable sales tax rate is 8%.
Convert the percentage into decimal form:
8 ÷ 100 = 0.08
Then calculate:
$100 × 0.08 = $8
Estimated sales tax:
$8
The final purchase price would be:
$100 + $8 = $108
This is a simple example of a sales tax on a 100 dollar purchase.
How to Calculate Price After Sales Tax
If you know the pre-tax price and applicable tax rate, use:
Total Price = Pre-Tax Price × (1 + Tax Rate)
For example, if you purchase an item costing $250 with an 8% sales tax:
$250 × 1.08 = $270
Your estimated total cost is:
$270
A purchase that initially appears to fit within a $250 budget would therefore require an additional $20.
If you make several taxable purchases during a month, those extra amounts can become relevant to your spending plan.
How to Find Sales Tax From Total Price
Sometimes you already know the final checkout price but want to determine how much of it represents sales tax.
This is called a reverse sales tax calculation.
Use:
Pre-Tax Price = Total Price ÷ (1 + Tax Rate)
Suppose the final price is $108 and the applicable rate is 8%.
$108 ÷ 1.08 = $100
The original price is $100.
The sales tax is:
$108 − $100 = $8
This can help when reviewing receipts, preparing expense reports, or tracking purchases that already include tax.
How to Calculate Sales Tax by State
Sales tax in the United States is not based on one nationwide retail tax rate.
The applicable rate can depend on the state, county, city, special taxing district, and type of purchase.
The Tax Foundation’s 2026 sales-tax analysis shows that combined state and local rates can differ significantly across jurisdictions.
For example, a state may have a statewide sales tax while individual cities or counties impose additional local taxes.
Some categories of goods may receive exemptions or different tax treatment.
Therefore, when using a sales tax calculator by state, check whether the selected rate includes applicable local taxes.
You can consult the Tax Foundation’s 2026 State and Local Sales Tax Rates for general comparisons and the relevant state revenue department for transaction-specific rules.
Add Sales Tax to Your Monthly Budget
Suppose you have allocated $400 each month for purchases that are all taxable at a hypothetical 8% rate.
Your estimated sales tax would be:
$400 × 0.08 = $32
If $400 represents your pre-tax spending, the total would be:
$432
However, if your $400 budget already includes sales tax, you should not add another $32.
The purpose is to include sales tax in your spending plan without counting the same expense twice.
Financial planning action: When setting a shopping budget, estimate the total amount you expect to pay at checkout, including applicable sales tax.
5. Calculate Tips and Shared Expenses
Financial planning is not limited to major purchases.
Restaurant visits, food deliveries, social events, and shared expenses can also affect your monthly spending.
A tip calculator helps you estimate the gratuity, calculate the final bill, and divide expenses among several people.
This is especially useful when dining with friends or family and deciding how much each person should contribute.
How to Calculate a Tip
The basic formula is:
Tip Amount = Tip Base × Tip Percentage
Suppose your restaurant bill before tax is $80.
If you choose to leave a 20% tip based on that amount:
$80 × 0.20 = $16
The tip would be:
$16
If the applicable sales tax is 8%:
$80 × 0.08 = $6.40
The complete bill would be:
$80 + $6.40 + $16 = $102.40
This example calculates the tip on the pre-tax bill. You can choose a different tip base or percentage according to your preferences and circumstances.
Before adding a tip, check whether the restaurant has already included a gratuity or service charge.
How to Calculate 15 Percent Tip
To calculate a 15% tip, multiply the amount you want to tip on by 0.15.
For a $60 restaurant bill:
$60 × 0.15 = $9
The tip is:
$9
If you are calculating the tip before tax, add any applicable sales tax separately to determine the final bill.
How to Calculate 20 Percent Tip
For a 20% tip, multiply the tip base by 0.20.
For an $80 bill:
$80 × 0.20 = $16
A 20% tip on that amount would equal $16.
These examples demonstrate the arithmetic; the amount you choose to tip may vary.
How Much to Tip on a Restaurant Bill
There is no single percentage that must be used in every tipping situation.
When deciding how much to tip on a restaurant bill, consider the type of service, your preferences, the restaurant’s billing practices, and any gratuity or service charge already included.
For budgeting purposes, it can be useful to estimate your total restaurant spending before deciding whether a particular outing fits your monthly allowance.
For example, if you plan to spend $100 in total, account for food, drinks, applicable taxes, and any tip you intend to leave.
How to Split a Bill With Tip
Suppose four friends share the $102.40 restaurant bill calculated earlier.
The total includes:
| Expense | Amount |
| Food and drinks | $80.00 |
| Sales tax | $6.40 |
| Tip | $16.00 |
| Final bill | $102.40 |
If everyone agrees to split the total equally:
$102.40 ÷ 4 = $25.60
Each person pays:
$25.60
If people ordered different amounts, calculate each person’s share of the food, tax, and agreed tip instead of assuming an equal split.
Include Restaurant Spending in Your Financial Plan
Suppose you dine out four times per month and your average total spending is $50 per visit, including taxes and tips.
Your estimated monthly restaurant budget is:
4 × $50 = $200
Over 12 months:
$200 × 12 = $2,400
Knowing this annual amount can help you decide how restaurant spending fits alongside other financial goals.
The purpose is not necessarily to eliminate discretionary spending. It is to make an informed decision about how much you want to allocate to it.
Financial planning action: Use a Tip Calculator to estimate the complete restaurant bill and add the total amount to your dining budget.
How to Combine All Five Calculations Into a Monthly Budget
Now that you understand the five calculators, the next step is bringing the results together.
The goal is to build a monthly budget that accounts for essential expenses, major financial commitments, everyday spending, and savings.
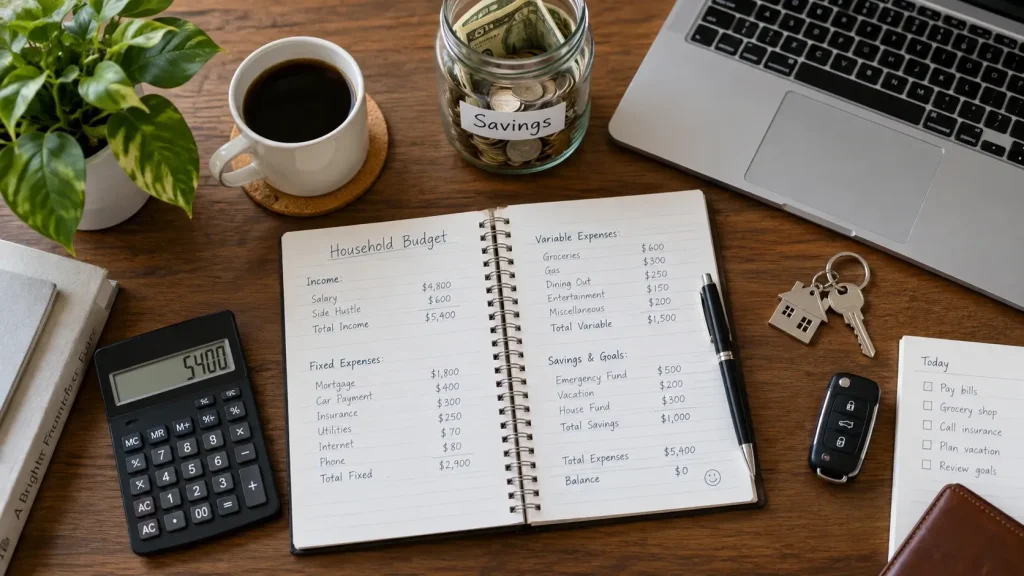
Example: Creating a $6,000 Monthly Financial Plan
Suppose a household receives $6,000 per month in take-home income.
After reviewing its housing costs, transportation needs, regular expenses, and savings goals, it creates the following illustrative budget:
| Budget category | Monthly amount |
| Housing | $2,100 |
| Transportation | $650 |
| Groceries, utilities, and other essentials | $1,300 |
| Savings | $900 |
| Dining, including taxes and tips | $300 |
| Other spending and irregular-expense allowance | $450 |
| Total planned spending and savings | $5,700 |
| Unallocated monthly balance | $300 |
This is an example, not a recommended allocation for every household.
The $300 remaining balance provides some flexibility, but the household may still need to consider debts, medical expenses, retirement contributions, or other obligations not fully represented in the example.
How Each Calculator Supports This Budget
The Mortgage Calculator helps the household estimate the housing payment and evaluate whether a property would fit within its planned housing budget.
The Auto Loan Calculator helps determine how much of the $650 transportation allocation could reasonably be used for a car payment after insurance, fuel, and maintenance.
The Compound Interest Calculator allows the household to explore what regular savings contributions might become over time under different hypothetical interest-rate assumptions.
The Sales Tax Calculator helps ensure that shopping expenses reflect actual checkout costs rather than only pre-tax prices.
The Tip Calculator helps estimate complete restaurant bills and allocate the appropriate amount to the dining budget.
Together, these financial planning tools provide a more complete picture of how the household’s spending decisions affect its remaining cash flow.
Avoid Counting Expenses Twice
When combining calculator results, pay attention to what is already included in each estimate.
If your mortgage calculator includes property taxes and homeowners insurance, do not add those expenses again under another budget category.
If your transportation budget includes the auto loan payment, do not list the same payment separately.
Similarly, if your grocery and dining budgets already use tax-inclusive prices, do not add estimated sales tax again.
The same applies to restaurant tips.
A useful financial plan should account for every relevant expense without counting any expense more than once.
How to Create a Financial Plan When Your Budget Is Tight
Not every household will have money left after paying essential expenses.
If your planned spending exceeds your take-home income, start by identifying which expenses can realistically be adjusted.
You may need to reconsider a proposed car purchase, delay a major purchase, review discretionary spending, or adjust the timing of a savings goal.
For example, if a new car payment would make your monthly budget negative, compare a lower-priced vehicle or postpone the purchase rather than assuming the financing offer is affordable because the lender approved it.
If you have high-interest debts, include their repayment requirements in your plan rather than focusing exclusively on savings projections.
Financial planning for beginners should be realistic and adaptable. Your starting plan does not have to be perfect, but it should reflect what your household can actually sustain.
Common Financial Planning Mistakes to Avoid
Even when you use accurate calculators, a financial plan can produce misleading results if your assumptions are unrealistic.
Using Gross Income Instead of Take-Home Pay
A common budgeting mistake is using your full salary before taxes and payroll deductions as if all of it were available to spend.
For everyday budgeting, start with actual take-home income.
Use gross income separately when a lender or another financial calculation specifically requires it.
Focusing Only on Loan Payments
A mortgage payment does not include every cost of owning a home.
A car payment does not include every cost of owning and operating a vehicle.
Include taxes, insurance, fees, maintenance, utilities, and other relevant expenses before deciding whether a major purchase fits your budget.
Assuming a Calculator Predicts the Future
Compound interest projections depend on the rate, contributions, time horizon, and other assumptions entered.
Actual savings rates and investment returns can differ from those assumptions.
Do not treat a hypothetical future value as guaranteed money.
Ignoring Irregular Expenses
Annual insurance premiums, car repairs, medical bills, holiday purchases, and seasonal expenses can disrupt a budget if you do not prepare for them.
Review previous spending and create an appropriate monthly allowance for expenses that do not occur every month.
Forgetting Sales Tax and Tips
A shopping budget based only on listed prices may underestimate what you pay.
Restaurant spending can also exceed the displayed menu prices once applicable taxes, gratuities, or service charges are included.
Use total purchase costs when planning spending.
Using Outdated Rates and Assumptions
Mortgage rates, auto-loan APRs, savings account rates, tax rules, and insurance premiums can change.
Recalculate important financial decisions using current information rather than relying entirely on old estimates.
Setting Unrealistic Savings Targets
A savings goal should be based on the amount you can contribute consistently.
Planning to save $1,000 per month when your income only leaves $300 after essential expenses is unlikely to produce a sustainable budget.
Adjust your target, spending plan, or timeline rather than relying on money that is not available.
Never Reviewing Your Financial Plan
Your finances will change over time.
A plan created today may no longer fit your circumstances after an income change, a new loan, or an increase in household expenses.
Review actual spending against your planned budget and make adjustments when needed.
Frequently Asked Questions
How do I create a financial plan for beginners?
Start by calculating your monthly take-home income, listing your expenses and debts, and identifying your savings goals. Use financial calculators to estimate major costs such as housing and transportation. Then create a monthly budget, track actual spending, and review your plan regularly.
What are the five essential calculators for financial planning?
The five calculators covered in this guide are the Mortgage Calculator, Auto Loan Calculator, Compound Interest Calculator, Sales Tax Calculator, and Tip Calculator. They help estimate housing costs, vehicle financing, potential savings growth, taxable purchases, and restaurant spending.
Are free online financial calculators accurate?
Free online financial calculators can provide useful estimates when they use appropriate formulas and you enter accurate information. However, actual loan payments, taxes, investment returns, and other financial costs can differ from the results because of changing rates, fees, and individual circumstances.
How much of my income should I spend on housing?
There is no single housing percentage that works for every household. Consider your take-home income, existing debts, savings goals, local taxes, insurance, maintenance, and other living expenses. A mortgage calculator can help you compare monthly payments under different home-price and financing scenarios.
How can I calculate my monthly car payment?
Enter the vehicle price, down payment, trade-in details, applicable taxes and fees, expected APR, and repayment term into an auto loan calculator. Review both the monthly payment and total borrowing cost before deciding whether the vehicle fits your budget.
How do I calculate compound interest with monthly contributions?
Enter your starting balance, monthly contribution, assumed interest rate, compounding frequency, and savings period into a compound interest calculator. It will estimate the future value based on those assumptions. Actual investment returns and savings rates may vary.
How much will my savings grow in 10 years?
The result depends on your initial balance, monthly contributions, assumed rate, compounding frequency, and any fees or withdrawals. For example, saving $200 at the end of each month for 10 years produces $24,000 in contributions before interest or investment growth.
How do I calculate sales tax on a $100 purchase?
Multiply the pre-tax price by the applicable sales tax rate. At a hypothetical 8% rate, sales tax on a $100 taxable purchase is $8, producing a final price of $108.
How do I calculate a 20 percent tip?
Multiply the amount you choose to tip on by 0.20. For example, a 20% tip on an $80 bill is $16. Add any applicable tax separately if it is not already included in the bill amount.
How do I split a restaurant bill with tax and tip?
Add the food and drink charges, applicable sales tax, and agreed gratuity. Divide the final amount by the number of people if everyone agrees to pay equally. If people ordered different amounts, calculate each person’s share separately.
Can I create a financial plan without hiring a financial advisor?
Yes. You can build a basic personal financial plan by reviewing your income, spending, debt, and savings goals and using financial calculators to estimate costs. More complicated situations involving investments, taxes, retirement, estate planning, or significant debts may benefit from advice from an appropriately qualified professional.
How often should I update my financial plan?
Review your monthly budget regularly and update your broader plan when income, major expenses, financial goals, debts, or household circumstances change. Recalculate major purchases when interest rates or financing terms change.
Final Takeaway
Learning how to create a financial plan does not require complicated financial software or advanced mathematics.
Start by understanding your take-home income, regular expenses, debts, and savings goals. Then use five essential calculators to estimate the financial commitments that affect your budget.
The Mortgage Calculator helps you evaluate housing expenses.
The Auto Loan Calculator helps you estimate vehicle financing and transportation costs.
The Compound Interest Calculator helps you explore potential savings growth over time.
The Sales Tax Calculator helps you calculate the full cost of taxable purchases.
The Tip Calculator helps you plan restaurant spending and shared bills.
Once you combine these calculations, you can create a monthly budget that reflects your priorities and financial circumstances.
Explore the My Panda Tools Financial Calculators to begin estimating your housing costs, transportation payments, savings goals, and everyday spending.
The purpose of financial planning is not to eliminate every discretionary purchase. It is to understand your financial position, make informed decisions, and establish a plan that can adapt as your circumstances change.