
A mortgage payment calculator can help you estimate how much you may need to pay each month before you apply for a home loan or make an offer on a property. Understanding that monthly payment is one of the most important parts of planning a home purchase because the cost of a mortgage goes beyond simply dividing the amount borrowed by the number of months in the loan.
Your mortgage payment can include principal, interest, property taxes, homeowners insurance, mortgage insurance, and other housing-related costs. The exact amount depends on your loan amount, interest rate, loan term, down payment, property location, and loan type.
If you want a fast estimate without calculating everything manually, use the Mortgage Calculator on My Panda Tools to enter your home price, down payment, interest rate, and loan term and estimate your monthly payment.
This guide explains how monthly mortgage payments work, how the formula is calculated, what costs you should include, and how to compare different mortgage scenarios before choosing a loan.
Quick Answer: How Do You Calculate a Monthly Mortgage Payment?
For a standard fixed-rate mortgage, your monthly principal and interest payment is calculated using four main values:
- Loan principal
- Interest rate
- Loan term
- Number of monthly payments
The standard mortgage formula is:
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
Where:
- M = monthly principal and interest payment
- P = principal or loan amount
- r = monthly interest rate
- n = total number of monthly payments
However, the result of this formula normally represents only principal and interest. Your actual monthly housing payment may also include property taxes, homeowners insurance, mortgage insurance, and other charges.
The Consumer Financial Protection Bureau explains that a borrower’s total monthly mortgage payment is usually higher than principal and interest because taxes, insurance, and potentially mortgage insurance may also be included.
What Is Included in a Monthly Mortgage Payment?
Before using a mortgage payment calculator, it helps to understand what you are actually estimating.
A mortgage payment is commonly explained using the term PITI:
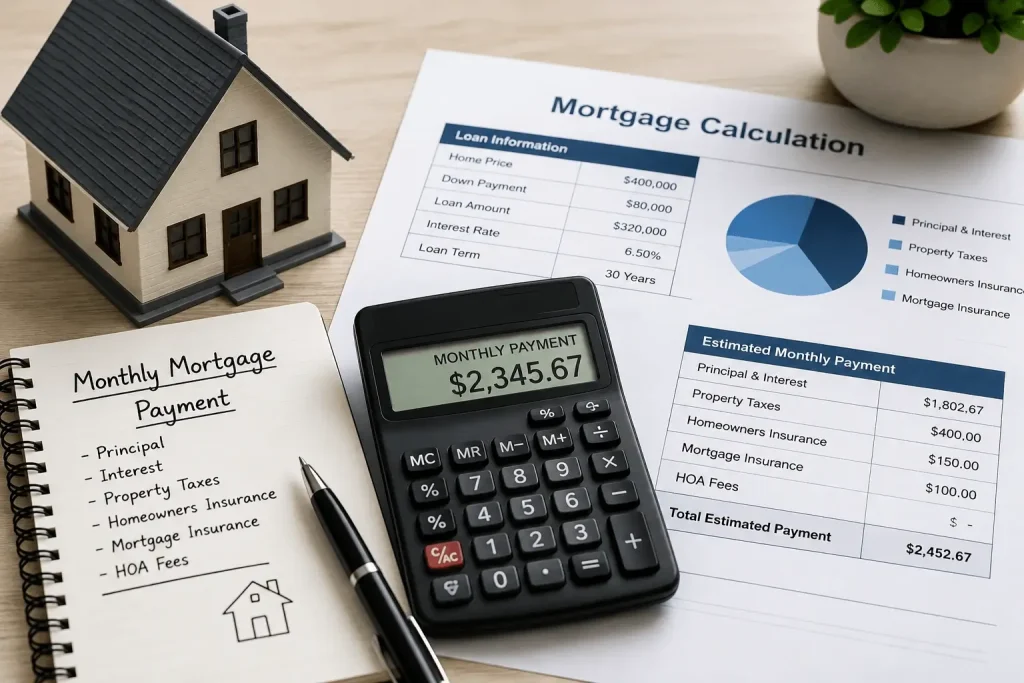
Principal
Principal is the amount of money you borrow from the lender.
For example, if a home costs $400,000 and you make an $80,000 down payment:
$400,000 − $80,000 = $320,000 loan principal
Your monthly mortgage payments gradually reduce this balance.
Interest
Interest is the cost charged by the lender for borrowing money.
The interest rate can significantly affect your payment. Even a relatively small change in the mortgage rate can change both your monthly payment and the total amount of interest paid over the life of the loan.
A mortgage rate calculator is useful when you want to compare how different rates may affect the same loan amount.
Property Taxes
Property taxes are generally assessed by state and local governments and vary significantly by location and property value.
When estimating your payment, divide the estimated annual property tax by 12.
For example:
$4,800 annual property tax ÷ 12 = $400 per month
Property taxes can change over time, so they should not be treated as permanently fixed.
Homeowners Insurance
Homeowners insurance protects against certain losses involving your property and belongings.
If your annual homeowners insurance premium were $1,800:
$1,800 ÷ 12 = $150 per month
Depending on the mortgage arrangement, taxes and insurance may be collected through an escrow account as part of the regular mortgage payment.
Mortgage Insurance
Some mortgages require mortgage insurance.
For conventional mortgages, private mortgage insurance may apply when the borrower makes a relatively small down payment. The CFPB notes that mortgage insurance is typically required when the down payment is less than 20% of the home’s purchase price, although requirements depend on the loan.
Government-backed mortgage programs may have their own mortgage insurance or funding-fee structures.
HOA Fees
If the home belongs to a homeowners association, you may also pay HOA dues.
HOA fees are generally separate from the mortgage payment, but they still affect your real monthly housing cost and should therefore be included in affordability planning.
Mortgage Payment Calculator Formula Explained
The formula used by a monthly mortgage calculator may look complicated at first, but each component is straightforward once you understand the inputs.
Suppose you have:
- Home price: $400,000
- Down payment: $80,000
- Loan amount: $320,000
- Interest rate: 6.5%
- Loan term: 30 years
First, determine the monthly interest rate.
6.5% ÷ 12 = approximately 0.5417% per month
For the formula, the percentage is expressed as a decimal:
0.065 ÷ 12 = 0.0054167
Next, calculate the total number of monthly payments:
30 years × 12 months = 360 payments
Using the mortgage formula, the estimated monthly principal and interest payment would be approximately:
$2,022.62 per month
That still is not necessarily your complete monthly home payment.
Suppose you also estimate:
- Property taxes: $400 per month
- Homeowners insurance: $150 per month
Then:
$2,022.62 + $400 + $150 = $2,572.62
Your estimated total monthly housing payment would therefore be approximately $2,572.62, before considering HOA fees or any applicable mortgage insurance.
This example shows why relying only on principal and interest can underestimate the real monthly cost of owning a home.
7 Easy Steps to Use a Mortgage Payment Calculator
1. Enter the Home Price
Start with the property’s purchase price.
If you are still comparing properties, try several price points. Doing this helps you understand how much your monthly cost might change when moving from one home-price range to another.
For example, calculate estimated payments for:
- $300,000 home
- $350,000 home
- $400,000 home
- $450,000 home
This is often more useful than beginning with the maximum amount a lender might approve.
Affordability should be based on your overall financial situation rather than only the maximum loan available to you.
2. Subtract Your Down Payment
Your down payment reduces the amount you need to borrow.
Use:
Home Price − Down Payment = Mortgage Principal
For example:
$400,000 − $80,000 = $320,000
A larger down payment generally reduces your loan principal and therefore lowers the principal-and-interest portion of your payment.
It may also affect mortgage insurance requirements.
When using a home loan calculator, always enter the actual amount you expect to finance rather than the home’s full purchase price.
3. Enter a Realistic Mortgage Interest Rate
Interest rate is one of the most important variables in mortgage calculations.
Do not assume that an advertised rate is automatically the rate you will receive.
A borrower’s mortgage terms can be influenced by factors such as:
- Credit profile
- Loan type
- Loan term
- Down payment
- Market conditions
- Discount points
- Property characteristics
- Lender pricing
If you have not yet received a formal mortgage quote, calculate more than one scenario.
For example, on a $320,000, 30-year fixed mortgage:
- At 6.0%, principal and interest is approximately $1,918.56
- At 6.5%, principal and interest is approximately $2,022.62
- At 7.0%, principal and interest is approximately $2,128.97
The difference between 6% and 7% is more than $200 per month in this example.
That is why comparing rates with a mortgage rate calculator can be useful before choosing a loan.
4. Choose the Loan Term
Common mortgage terms include:
- 15 years
- 20 years
- 30 years
A longer loan term generally results in a lower required monthly principal-and-interest payment, but you may pay interest for a longer period.
A shorter term usually produces a higher monthly payment but can reduce the total interest paid if the loan is kept for its full term.
For example, compare the same loan using the mortgage payment calculator with both a 15-year and a 30-year term.
Do not choose based only on the lowest monthly payment. Consider your budget, expected time in the home, emergency savings, retirement contributions, and other financial priorities.
5. Add Estimated Property Taxes
Your mortgage formula does not automatically know your local tax bill.
Property taxes differ from one location to another, so use a property-specific estimate whenever possible.
If annual property taxes are $6,000:
$6,000 ÷ 12 = $500 per month
Add that $500 to your monthly mortgage estimate.
Taxes can also change after purchasing the property. This means your future total payment could change even when you have a fixed-rate mortgage.
6. Add Insurance and Mortgage Insurance
Next, include homeowners insurance.
Divide the estimated annual premium by 12.
If applicable, also add mortgage insurance.
This step matters because a monthly mortgage calculator that displays only principal and interest can make a property appear more affordable than it really is.
The CFPB recommends considering property taxes and homeowners insurance when determining what total monthly home payment you can afford.
7. Compare Multiple Scenarios
Do not calculate only one mortgage scenario.
Compare combinations of:
- Different home prices
- Different down payments
- Different rates
- 15-year versus 30-year terms
- Different property-tax estimates
- Mortgage insurance versus no mortgage insurance
For example, ask:
What happens if the mortgage rate increases by 0.5%?
What happens if I put an additional $20,000 down?
What happens if I choose a less expensive home?
What happens if property taxes are higher than expected?
Using a mortgage payment calculator for scenario planning can be more valuable than generating a single payment estimate.
Mortgage Payment Calculator vs. Mortgage Quote
A calculator estimate and a mortgage quote are not the same thing.
A mortgage payment calculator produces an estimate based on the numbers you enter.
A mortgage quote comes from a lender and may reflect specific loan pricing based on your financial profile, the property, the loan program, and current market conditions.
You should therefore use calculator results for planning rather than treating them as a guaranteed lender offer.
Once you formally apply for a mortgage, lenders generally provide a standardized Loan Estimate containing important information such as the estimated interest rate, monthly payment, closing costs, taxes, and insurance.
According to the CFPB, lenders generally must provide a Loan Estimate within three business days after receiving a mortgage application.
Compare that document with your initial calculator estimate.
Mortgage Rate Calculator: Why Interest Rates Matter
Interest rates affect more than your first monthly payment.
A higher rate means a larger portion of your payment goes toward interest, particularly during the earlier years of a traditional amortizing mortgage.
Consider again a $320,000, 30-year mortgage:
| Interest Rate | Approx. Monthly Principal & Interest |
|---|---|
| 6.0% | $1,918.56 |
| 6.5% | $2,022.62 |
| 7.0% | $2,128.97 |
The home price and loan amount remain exactly the same. Only the rate changes.
This makes a mortgage rate calculator particularly useful when comparing lender offers.
However, rate should not be the only comparison point.
Also review:
- APR
- Discount points
- Origination fees
- Closing costs
- Mortgage insurance
- Prepayment penalties
- Adjustable-rate features
- Cash required at closing
The CFPB recommends comparing Loan Estimates from multiple lenders because interest rates and loan costs can differ, and multiple estimates can help consumers compare and potentially negotiate loan offers.
How a Home Loan Calculator Helps With Affordability
A home loan calculator helps answer a slightly different question from simply asking how much your mortgage payment will be.
Instead of asking:
“How much can I borrow?”
A better question is:
“What monthly housing cost fits comfortably within my budget?”
Consider expenses such as:
- Mortgage payment
- Utilities
- Home maintenance
- Repairs
- HOA fees
- Property taxes
- Insurance
- Transportation
- Credit-card payments
- Auto loans
- Student loans
- Childcare
- Emergency savings
- Retirement contributions
A lender’s approval amount and your comfortable household budget are not necessarily the same.
Use the estimated mortgage payment as one component of a larger homeownership budget.
Fixed-Rate vs. Adjustable-Rate Mortgage Payments
With a traditional fixed-rate mortgage, the interest rate remains fixed for the loan term.
As a result, scheduled principal and interest payments generally remain consistent.
Your total housing payment can still change because property taxes, homeowners insurance, and some other costs may increase or decrease.
An adjustable-rate mortgage, or ARM, works differently.
After an initial fixed-rate period, the interest rate may adjust according to the loan’s terms. That means future principal-and-interest payments can change.
The CFPB specifically advises borrowers considering loans with changing rates or payments to understand how much the payment could increase.
If comparing an ARM with a fixed-rate loan, do not calculate only the introductory payment. Review potential future payments as well.
Common Mortgage Payment Calculation Mistakes
Using the Home Price Instead of the Loan Amount
If a home costs $400,000 but you put $80,000 down, your mortgage principal is generally $320,000—not $400,000.
Ignoring Taxes and Insurance
Principal and interest alone do not represent the entire cost of homeownership.
Include taxes and insurance for a more useful monthly estimate.
Forgetting Mortgage Insurance
A smaller down payment may result in additional mortgage insurance costs depending on the loan.
Assuming Today’s Estimate Is Guaranteed
A calculator is an educational planning tool.
Actual lender terms may differ.
Using an Unrealistic Interest Rate
Testing an unusually low rate can make a home look artificially affordable.
Use a realistic range and compare several scenarios.
Ignoring HOA Fees
HOA dues may not be technically part of your mortgage payment, but they still affect your monthly housing budget.
Comparing Loans Only by Monthly Payment
A lower payment does not automatically mean a less expensive mortgage.
A longer loan term, for example, may reduce monthly payments while increasing the length of time you pay interest.
How to Lower an Estimated Monthly Mortgage Payment
Several variables can reduce a projected payment.
Buy a Lower-Priced Home
A smaller mortgage principal generally means a lower monthly principal-and-interest payment.
Make a Larger Down Payment
A larger down payment reduces the amount borrowed and may affect mortgage insurance requirements.
Compare Mortgage Rates
Even a modest rate difference can affect monthly and long-term borrowing costs.
Use the mortgage rate calculator and compare formal lender estimates before making a final decision.
Consider a Longer Loan Term
A longer repayment term can reduce the required monthly principal-and-interest payment, although it can increase long-term interest costs.
Improve Your Financial Profile Before Applying
Depending on the lender and loan program, factors such as credit history, debt levels, cash reserves, income, and down payment may affect available mortgage terms.
How to Compare Mortgage Quotes
Once you start receiving mortgage quotes, compare them using the same loan assumptions.
Check:
- Loan amount
- Loan term
- Interest rate
- APR
- Monthly principal and interest
- Mortgage insurance
- Estimated taxes and insurance
- Origination charges
- Discount points
- Total closing costs
- Cash to close
- Rate-lock information
A lower advertised interest rate does not automatically mean the loan has the lowest overall cost.
For formal applications, use the standardized Loan Estimate to make a more accurate side-by-side comparison.
Use the My Panda Tools Mortgage Payment Calculator
Manually calculating mortgage payments is useful for understanding how the math works, but you do not need to repeat the formula every time you compare a property.
Use the My Panda Tools Mortgage Calculator to quickly estimate a monthly mortgage payment using your own numbers.
You can test different:
- Home prices
- Loan amounts
- Down payments
- Mortgage rates
- Loan terms
Changing one variable at a time can help you see which factors have the greatest impact on your estimated monthly cost.
For additional financial planning, explore the Financial Calculators section on My Panda Tools.
A mortgage payment calculator gives homebuyers a practical starting point for understanding one of the largest recurring expenses associated with homeownership.
Start with the home price and down payment to calculate the amount you need to borrow. Then enter the mortgage rate and loan term to estimate principal and interest. Finally, add property taxes, homeowners insurance, mortgage insurance when applicable, and other recurring housing expenses.
Remember that a calculator provides an estimate—not a lender commitment or guaranteed mortgage quote.
The most useful approach is to calculate several scenarios, compare mortgage rates, review total monthly housing costs, and then compare the estimates with the official loan documents provided by lenders.
That process gives you a clearer picture of what a home may actually cost each month and can help you make a more informed borrowing decision.
Frequently Asked Questions About Monthly Mortgage Payments
How do I calculate my monthly mortgage payment?
For a fixed rate mortgage, monthly principal and interest are calculated using the loan amount, monthly interest rate, and total number of monthly payments. You should then add estimated property taxes, homeowners insurance, mortgage insurance when applicable, and other housing costs to estimate your total monthly payment.
What is the formula for calculating a mortgage payment?
The standard formula is:
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
Here, M is the monthly payment, P is the loan principal, r is the monthly interest rate, and n is the total number of payments.
Does a mortgage payment calculator include property taxes?
It depends on the calculator. Some calculate only principal and interest, while more complete calculators allow you to add property taxes, insurance, and mortgage insurance. Always check which costs are included in the result.
What is included in a monthly mortgage payment?
A typical mortgage-related payment may include principal, interest, property taxes, homeowners insurance, and mortgage insurance. HOA fees may be an additional separate housing expense.
How much is the monthly payment on a $300,000 mortgage?
The answer depends primarily on the interest rate and loan term, plus taxes, insurance, and other costs. Enter the $300,000 loan amount, your expected rate, and your loan term into a monthly mortgage calculator for a relevant estimate.
Does a bigger down payment lower my monthly mortgage payment?
Generally, yes. A larger down payment reduces the amount you need to borrow, which normally reduces the principal-and-interest payment. It may also affect mortgage insurance requirements.
How does the mortgage interest rate affect my payment?
A higher mortgage rate increases the interest cost associated with borrowing and normally increases the required principal-and-interest payment for the same loan amount and term.
Is a mortgage calculator the same as a mortgage quote?
No. A calculator provides an estimate based on information you enter. A mortgage quote or Loan Estimate from a lender reflects specific loan terms and costs associated with an actual mortgage application or offer.
Can my mortgage payment increase on a fixed-rate loan?
Your scheduled principal-and-interest payment generally remains stable on a traditional fixed-rate mortgage, but your total payment can change if property taxes, homeowners insurance, mortgage insurance, or escrow requirements change.
What is the best way to compare monthly mortgage payments?
Calculate several scenarios using the same home price and loan amount but different interest rates, down payments, and loan terms. Then compare your estimates with Loan Estimates from lenders and evaluate both monthly and long-term costs.